
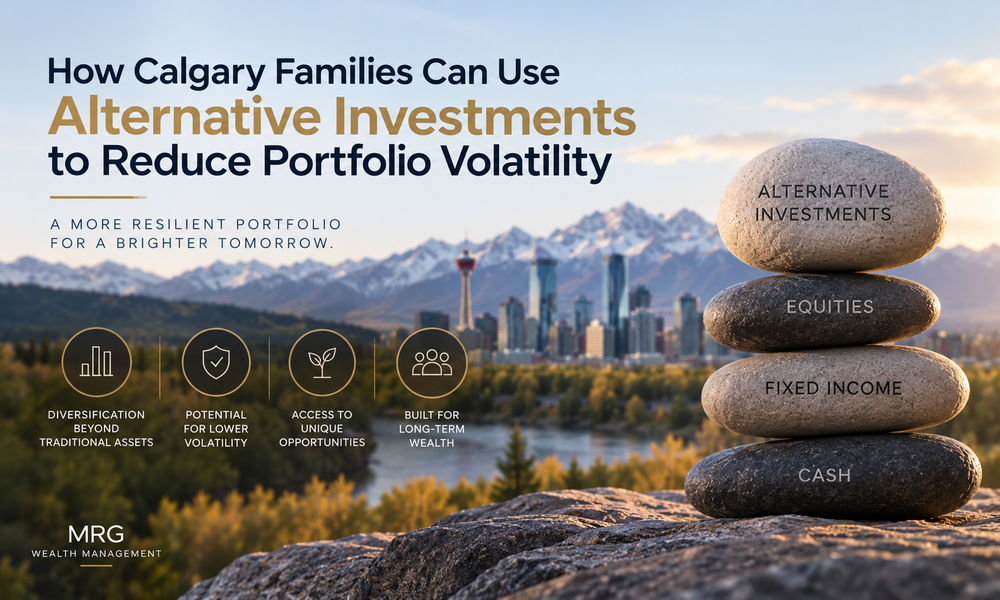
How Calgary Families Can Use Alternative Investments to Reduce Portfolio Volatility
Alternative investments can offer institutional-grade diversification with lower volatility
Written by
Ryan Gubic
Published on
5
Oct 2026
Copy link
For most Calgary investors, a portfolio means stocks and bonds. Maybe some GICs. A mix that shifts more conservative as retirement approaches. It's the standard model, and for decades it worked reasonably well.
But the families working with wealth management Calgary professionals at the ultra high networth level have been doing something different for a long time - and the gap between what they access and what the average retail investor can access is significant.
Alternative investments have been a core component of how pension funds, endowments, and ultra-high-net-worth families manage wealth for decades. For Calgary investors with $500,000 or more in investable assets, access to that same category of investment is now possible - and the case for including it is worth understanding.
What Alternative Investments Actually Are
The term gets used loosely, but in the context of a well-structured wealth management strategy, alternatives typically refer to private credit, private real estate, and infrastructure investments. These are assets that don't trade on public markets, which is precisely what makes them valuable from a portfolio construction standpoint.
Because they don't trade daily, they're not subject to the same volatility cycles that hit public equity markets. When stock markets dropped sharply in 2020, or experienced the drawdown of 2022, portfolios with meaningful alternative allocations held up measurably better - not because the underlying assets were worth more, but because their valuations don't move in lockstep with public market sentiment.
The Historical Case for Alternatives
Institutional investors - CPP, university endowments, large pension funds - have allocated heavily to alternatives for decades precisely because the data supports it. Private credit has historically delivered attractive results with lower volatility than public fixed income. Private real estate and infrastructure have provided consistent cash flow and inflation protection that bonds increasingly struggle to deliver in a rising rate environment.
The reason most retail investors don't hold these assets isn't that they're inappropriate for their situation. It's that access has historically required large minimum investments per fund, putting them out of reach for anyone without institutional scale or a wealth management relationship that aggregates client capital to meet those minimums.
How the Personal CFO Model Changes Access
One of the core differentiators of working with a Personal CFO at MRG Wealth is access to institutional-quality alternative investments that aren't available through a standard brokerage account or a typical advisory relationship.
Through our investment platform, Calgary families with $500,000 or more in investable assets can access the same private credit, private real estate, and infrastructure strategies that have historically been available only to pension funds and ultra-high-net-worth investors. These strategies are integrated into a broader portfolio alongside public equity and fixed income, with allocations calibrated to each client's specific goals, timeline, and tax situation.
The result is a portfolio that participates in long-term market growth while carrying meaningfully less volatility than an all-public-market approach - which matters most when markets drop and clients are closest to or in retirement.
What a Portfolio With Alternatives Actually Looks Like
A well-constructed portfolio for a Calgary family in their late 40s or early 50s with a 10-15 year retirement horizon and right risk tolerance might allocate a portion to quality alternatives. For example, split across private credit for income and stability, private real estate for inflation protection and cash flow, and infrastructure for long-duration, low-correlation returns. It is important to review your specific circumstances with a trusted professional.
The remaining allocation could sit in global public equity for long-term growth and a modest fixed income component for liquidity and ballast. The overall effect is a portfolio that grows through market cycles rather than lurching through them - which has a compounding effect not just on returns but on investor behaviour, since clients who aren't watching their portfolio drop 25% in a correction are far less likely to make the reactive decisions that permanently impair long-term outcomes.
Is This the Right Fit for Your Situation?
Alternative investments aren't appropriate for every investor or every situation. They carry liquidity constraints - meaning capital committed to a private credit or real estate fund typically isn't accessible on short notice - so they work best as part of a broader strategy where liquidity needs are already covered by other assets.
For Calgary families with $500,000 or more in investable assets, appropriate risk tolerance, and a financial plan that accounts for liquidity needs separately, the case for including alternatives is strong and the access is now available through the right advisory relationship.
If you have questions, let's talk and discover the wealth management Calgary families trust to have clarity, confidence, and freedom in their financial life.
Ready to See What a Portfolio Built for Your Situation Looks Like?
Book a 30-minute intro call and we'll walk through your current allocation, identify where alternatives might fit, and show you what a coordinated strategy looks like for your specific circumstances.
Ryan Gubic is the founder of MRG Wealth Management Inc. operating as MRG Wealth (“MRG”) and is a Portfolio Manager with MRG investments of Aligned Capital Partners Inc. (“ACPI”). The opinions expressed are not necessarily those of MRG, ACPI, or Ryan Gubic. This material is provided for general information and the opinions expressed and information provided herein are subject to change without notice. Every effort has been made to compile this material from reliable sources however no warranty can be made as to its accuracy or completeness. Before acting on the information presented, seek professional financial advice based on your personal circumstances. ACPI is a full-service investment dealer and a member of the Canadian Investor Protection Fund (“CIPF”) and the Canadian Investment Regulatory Organization (“CIRO”). Investment services are provided through MRG Investments, an approved trade name of ACPI. Only investment-related products and services are offered through MRG Investments of ACPI and covered by the CIPF. Financial planning and insurance services are provided through MRG. MRG is an independent company separate and distinct from MRG Investments of ACPI.
Dollars and Sense
Discover more
Dive into some advice directly from our Founder and Personal CFO.
What Happened in the Markets in September 2026