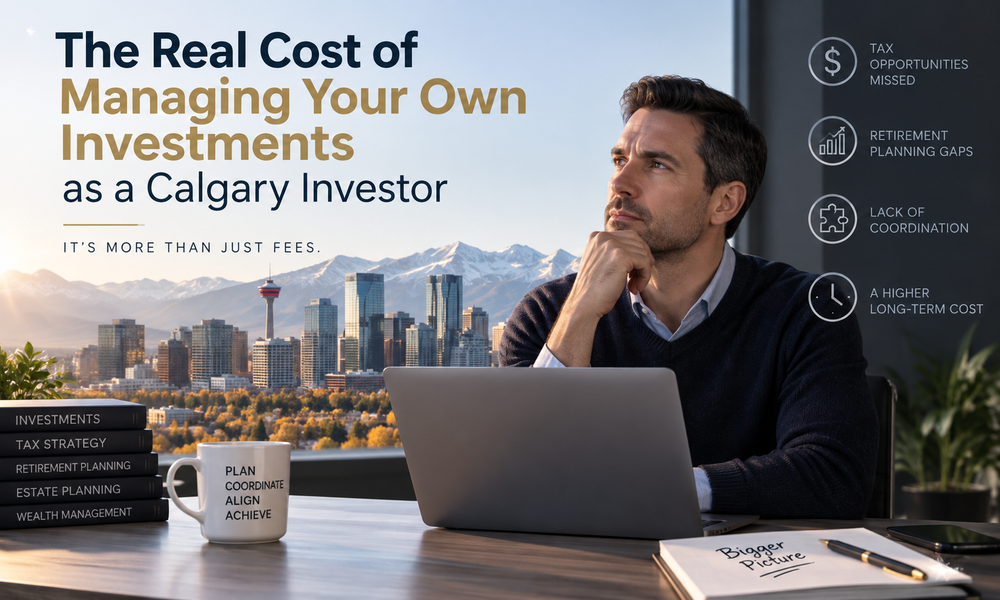
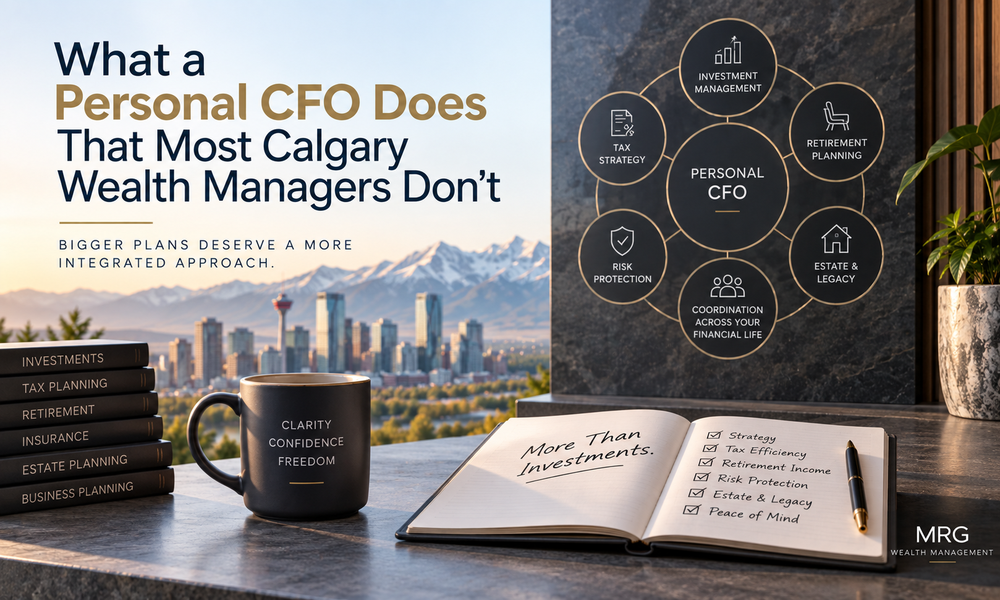
What a Personal CFO Does That Most Calgary Wealth Managers Don't
The Personal CFO model coordinates investments, taxes, retirement, estate, insurance, and cash flow under one advisor
Written by
Ryan Gubic
Published on
28
Sep 2026
Copy link
If you've worked with a financial advisor in Calgary before, you probably experienced a version of the same relationship. You met once or twice a year, reviewed your portfolio performance, made some adjustments, and went back to managing the rest of your financial life on your own.
For many Calgary families seeking wealth management Calgary professionals trust, that model eventually stops being enough. When your assets are significant and your financial picture is complex, a fragmented approach is quietly costing you more than you realize.
The Personal CFO model is different - and the difference matters.
What a Traditional Wealth Manager Actually Does
Most wealth managers in Calgary are investment managers first. Their primary job is to build and manage your portfolio, report on its performance, and make adjustments as markets change. That's valuable work, but it's a narrow mandate.
The problem is that your investment portfolio doesn't exist in isolation. It sits inside a larger financial picture that includes your tax situation, your retirement timeline, your corporate structure if you're a business owner, your estate intentions, your insurance coverage, and your cash flow. A wealth manager focused primarily on portfolio performance isn't looking at how those pieces interact - and that's where the most costly gaps tend to live.
What the Personal CFO Model Changes
A Personal CFO operates with a fundamentally different mandate. Instead of managing one component of your financial life, they coordinate all of it - functioning as a chief financial officer for your household rather than simply a portfolio manager.
In practice, this means your investment decisions are made with your tax situation in mind. Your account structures are designed around your retirement income sequencing, not just your risk tolerance. Your estate intentions are reflected in how your assets are held and titled. Your insurance coverage is reviewed in the context of your overall financial plan, not sold to you as a standalone product.
The goal is to ensure that every financial decision you make is made with the full picture in view - and that decisions in one area don't create unintended consequences in another.
The Six Areas a Personal CFO Coordinates
The Vantage System that underpins the Personal CFO model at MRG Wealth integrates six interconnected areas of your financial life into a single coordinated strategy.
Investment management sits at the core, but it's designed around your specific goals, timeline, and tax situation rather than a generic risk profile. This includes access to institutional-quality alternative investments - private credit, private real estate, infrastructure - that most retail investors can't access on their own and that have historically provided returns less correlated with public markets.
Tax planning coordinates your investment decisions with your tax situation in real time. This means asset location across account types, capital gains timing, RRSP and TFSA optimization, and retirement income sequencing designed to minimize your lifetime tax bill rather than just your current year's return.
Retirement planning builds a comprehensive projection of your retirement income from every source - CPP, OAS, registered accounts, non-registered accounts, and any pension or business income - and models how that picture changes under different market and timing scenarios.
Estate planning ensures your assets transfer to the right people in the most efficient way, with beneficiary designations, account structures, and estate documents that are reviewed and updated as your life changes rather than filed and forgotten.
Insurance planning reviews your coverage in the context of your overall financial plan - not to sell you more insurance, but to ensure what you have is still appropriate for your current situation and that gaps aren't quietly creating risk.
Cash flow and debt management looks at how your income is being allocated and whether your debt structure is serving your long-term wealth goals, particularly for Calgary families with mortgages, investment loans, or corporate structures.
Why the Coordination Matters More Than Any Individual Component
Here's the biggie. Most Calgary families with significant assets are already doing most of these things. They have an advisor managing their investments. They have an accountant doing their taxes. They have a lawyer who drafted their will. They have an insurance policy they bought years ago.
But none of those professionals are talking to each other. And the gaps between those relationships - the places where a decision made in one area creates an unintended consequence in another - are where the most meaningful planning opportunities go unrecognized and the most costly mistakes happen quietly over time.
The Personal CFO model eliminates those gaps by putting one advisor in a coordinating role with visibility across your entire financial picture. Not replacing your accountant or your lawyer, but ensuring that what they're doing is integrated with your investment and planning strategy rather than happening in parallel with no connection.
For Calgary families with $500,000 or more in investable assets, the value of that coordination compounds over time in ways that show up most clearly at retirement - in lower taxes paid over a lifetime, in a retirement income plan that actually holds under pressure, and in an estate that transfers the way you intended.
Is a Personal CFO the Right Fit for Your Situation?
The families who benefit most from the Personal CFO model are typically Calgary professionals, executives, or business owners in their 40s or 50s who have built significant wealth but feel like their financial picture is more complicated than it should be. They suspect they're leaving money on the table somewhere - in taxes, in investment structure, in planning they haven't gotten around to - but they don't have a clear picture of where.
If that description fits, the right next step is a conversation.
If you have questions, let's talk and discover the wealth management Calgary families trust to have clarity, confidence, and freedom in their financial life.
Ready to See What a Coordinated Financial Strategy Looks Like for Your Family?
Book a 30-minute intro call and we'll clarify where you stand, identify the gaps in your current plan, and show you what the Personal CFO model delivers for your specific situation.
Ryan Gubic is the founder of MRG Wealth Management Inc. operating as MRG Wealth (“MRG”) and is a Portfolio Manager with MRG investments of Aligned Capital Partners Inc. (“ACPI”). The opinions expressed are not necessarily those of MRG, ACPI, or Ryan Gubic. This material is provided for general information and the opinions expressed and information provided herein are subject to change without notice. Every effort has been made to compile this material from reliable sources however no warranty can be made as to its accuracy or completeness. Before acting on the information presented, seek professional financial advice based on your personal circumstances. ACPI is a full-service investment dealer and a member of the Canadian Investor Protection Fund (“CIPF”) and the Canadian Investment Regulatory Organization (“CIRO”). Investment services are provided through MRG Investments, an approved trade name of ACPI. Only investment-related products and services are offered through MRG Investments of ACPI and covered by the CIPF. Financial planning and insurance services are provided through MRG. MRG is an independent company separate and distinct from MRG Investments of ACPI.
Dollars and Sense
Discover more
Dive into some advice directly from our Founder and Personal CFO.
What Happened in the Markets in August 2026