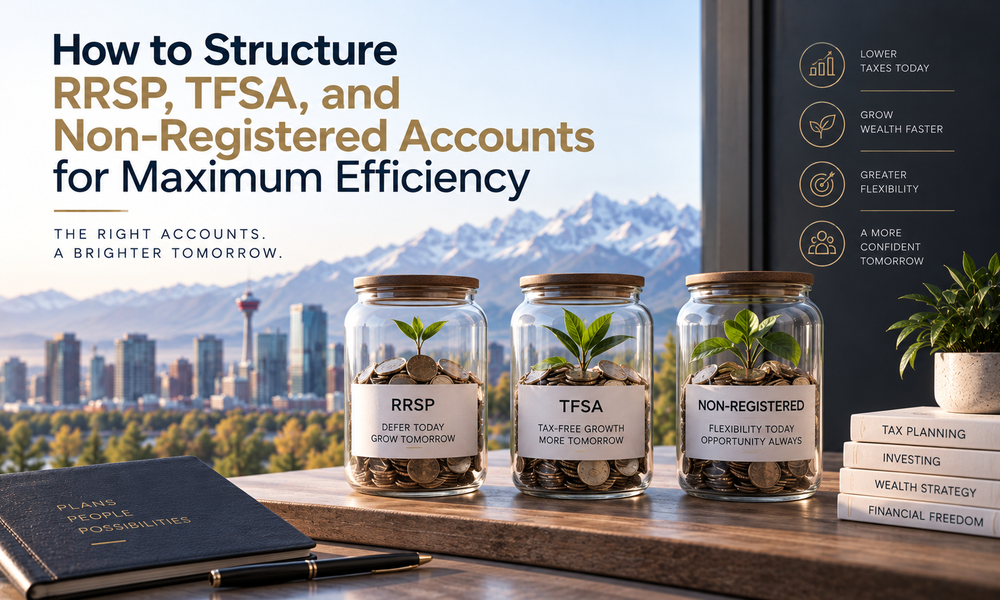
How to Structure RRSP, TFSA, and Non-Registered Accounts for Maximum Efficiency
Where you hold investments matters as much as what you hold—smart RRSP/TFSA/non-registered structuring and withdrawal sequencing can save Calgary investors real money in lifetime tax.
Written by
Ryan Gubic
Published on
26
Oct 2026
Copy link
For Calgary investors with significant assets, the question of which investments to hold is sometimes less important than the question of where to hold them. Account structure - how your money is distributed across your RRSP, TFSA, and non-registered accounts - has a direct and measurable impact on your after-tax returns, your retirement income, and your lifetime tax bill.
Most Calgary families working with wealth management Calgary professionals at the integrated planning level discover that their account structure is costing them more than their investment selection ever has. Not because of bad decisions, but because nobody has ever looked at the full picture with tax efficiency as the organizing principle.
Here's how to think about it correctly.
Understanding What Each Account Actually Does
The three main account types available to Calgary investors serve fundamentally different tax functions, and those functions should drive how you use them.
Your RRSP defers tax. Contributions reduce your taxable income today, investments grow without annual tax drag, and withdrawals are taxed as income when you take them out - ideally in retirement when your marginal rate is lower than it was during your peak earning years. The RRSP is most powerful when the tax rate at contribution is higher than the tax rate at withdrawal. For high-income Calgary professionals, that gap can be substantial.
Your TFSA shelters tax permanently. There's no deduction on the way in, but every dollar of growth and every withdrawal is completely tax-free, forever. The TFSA doesn't interact with your income at all - withdrawals don't affect your marginal rate, your OAS eligibility, or any income-tested benefits. For high-income Calgary investors, this makes the TFSA extraordinarily valuable as a long-term growth vehicle, not a savings account.
Your non-registered account is fully taxable but offers the most flexibility. Capital gains are taxed at half your marginal rate when realized. Canadian eligible dividends receive a dividend tax credit. Interest income is taxed at your full marginal rate. The tax treatment of what you hold in a non-registered account varies significantly by investment type, which is precisely why asset location matters.
RRSP Withdrawal Strategy and Retirement Income Sequencing
The decisions you make about when and how to draw from your RRSP in retirement have a larger impact on your lifetime tax bill than almost any investment decision you'll make before you get there.
The default approach - leaving your RRSP untouched until you're forced to convert it to a RRIF at 71 and take mandatory minimum withdrawals - often results in large, heavily taxed withdrawals later in retirement that push you into higher marginal brackets and can trigger OAS clawback. For Calgary investors with significant RRSP balances, this is a meaningful and avoidable problem.
A better approach involves drawing down RRSP assets strategically in the years between retirement and age 71, keeping annual withdrawals within a tax bracket that makes sense for your overall income picture. For couples, coordinating withdrawals with spousal RRSP income, CPP timing, and OAS deferral decisions creates a retirement income plan that minimizes lifetime tax across both spouses rather than optimizing each account in isolation.
The TFSA Sequencing Opportunity
One of the most powerful but underused retirement planning tools for Calgary investors is the strategic sequencing of TFSA withdrawals in retirement. Because TFSA withdrawals don't count as income, they can be used to fill income gaps without affecting your marginal rate, your OAS eligibility, or any income-tested credits.
This creates an opportunity to draw RRSP or RRIF income up to the top of a favorable tax bracket, then supplement with tax-free TFSA withdrawals rather than triggering additional taxable income. Over a 20-30 year retirement, that sequencing strategy can save tens of thousands of dollars in tax that would otherwise be paid unnecessarily.
The TFSA withdrawal room also restores the following January, which means strategic partial withdrawals in one year can be recontributed in the next - creating ongoing flexibility that most investors don't fully leverage.
Corporate Account Coordination for Business Owners
For Calgary business owners with retained earnings inside a corporation, the account structure question extends beyond personal registered accounts to include the interaction between corporate investment income and personal withdrawal strategies.
Corporate retained earnings can be invested inside the corporation, but the passive income rules introduced in 2018 mean that significant corporate investment income can reduce the small business deduction available on active income - creating a tax consequence that catches many business owners off guard. Managing the timing and structure of corporate investments, coordinating corporate distributions with personal registered account contributions, and planning the eventual transition of corporate assets into personal hands requires integrated planning that looks at both the corporate and personal picture simultaneously.
For Calgary business owners approaching retirement or a business sale, getting this coordination right in the years before the liquidity event can make a dramatic difference in after-tax proceeds.
Why Structure Matters
Here's the biggie. Most Calgary investors spend the majority of their financial attention on investment selection - which funds to hold, how to allocate between asset classes, whether to add or reduce equity exposure. These decisions matter, but they operate at the margin.
Account structure and withdrawal sequencing operate at the foundation. Getting them right doesn't require finding better investments - it requires looking at your full financial picture with tax efficiency as the organizing principle and making deliberate decisions about where each dollar sits and when each account gets drawn.
For Calgary families with $500,000 or more in investable assets across multiple account types, that structural optimization is often the single highest-value planning exercise available - and it's almost never done without an advisor who is looking at everything together.
If you have questions, let's talk and discover the wealth management Calgary families trust to have clarity, confidence, and freedom in their financial life.
Ready to Find Out If Your Account Structure Is Working Against You?
Book a 30-minute intro call and we'll review how your assets are currently structured, identify the optimization opportunities available in your situation, and show you what a tax-efficient account strategy looks like for your specific circumstances.
Ryan Gubic is the founder of MRG Wealth Management Inc. operating as MRG Wealth (“MRG”) and is a Portfolio Manager with MRG investments of Aligned Capital Partners Inc. (“ACPI”). The opinions expressed are not necessarily those of MRG, ACPI, or Ryan Gubic. This material is provided for general information and the opinions expressed and information provided herein are subject to change without notice. Every effort has been made to compile this material from reliable sources however no warranty can be made as to its accuracy or completeness. Before acting on the information presented, seek professional financial advice based on your personal circumstances. ACPI is a full-service investment dealer and a member of the Canadian Investor Protection Fund (“CIPF”) and the Canadian Investment Regulatory Organization (“CIRO”). Investment services are provided through MRG Investments, an approved trade name of ACPI. Only investment-related products and services are offered through MRG Investments of ACPI and covered by the CIPF. Financial planning and insurance services are provided through MRG. MRG is an independent company separate and distinct from MRG Investments of ACPI.
Dollars and Sense
Discover more
Dive into some advice directly from our Founder and Personal CFO.
Your Financial Plan Looks Great, But Does Your Estate Plan Actually Support It?