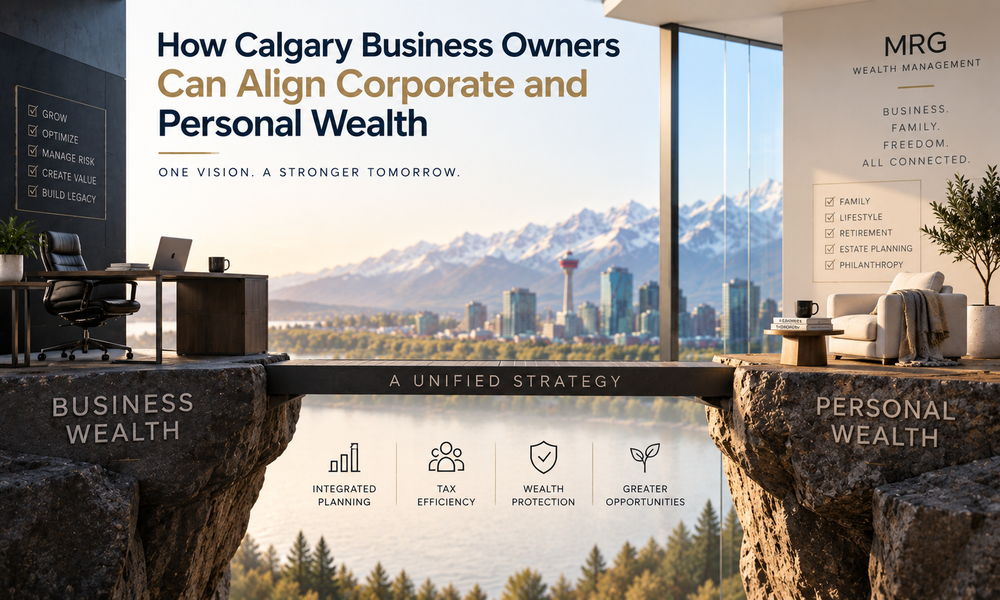
How Calgary Business Owners Can Align Corporate and Personal Wealth
Corporate and personal finances need one coordinated plan—compensation strategy, passive income limits, exemption planning, and wealth transition all work best managed together.
Written by
Ryan Gubic
Published on
9
Nov 2026
Copy link
For Calgary business owners, the line between corporate and personal finances is rarely as clean as it should be. Money moves between the corporation and the household in ways that feel pragmatic in the moment but often create tax inefficiencies, missed planning opportunities, and structural problems that compound quietly over years.
The families who get this right aren't necessarily doing more complex things. They're doing the same things with a financial advisor Calgary business owners at the significant asset level work with - someone who holds both the corporate and personal picture simultaneously and ensures decisions made in one don't create unintended consequences in the other.
Here's what that coordination actually looks like.
The Core Problem With Keeping Corporate and Personal Separate
Most Calgary business owners work with an accountant who handles the corporate tax return and a separate investment advisor who manages personal registered accounts. Those two professionals are rarely talking to each other, and the gap between their mandates is where the most expensive planning oversights tend to live.
Your corporate retained earnings affect your personal tax position. Your personal withdrawal strategy affects your corporate passive income and potentially your small business deduction. Your RRSP room is driven by your T4 compensation from the corporation. Your retirement income plan depends on how corporate assets eventually transition to personal hands. These aren't separate decisions - they're one interconnected system that needs to be managed as such.
When they're managed separately, the result is usually not a catastrophic mistake. It's a slow accumulation of missed opportunities that only becomes visible when someone finally looks at the full picture and calculates what better coordination would have been worth over the previous decade.
Compensation Strategy - Salary Versus Dividends
One of the most consequential annual decisions for Calgary business owners is how to draw income from the corporation - through salary, dividends, or a combination of both.
Salary creates RRSP contribution room, counts as earned income for CPP purposes, and is deductible to the corporation. Dividends are more tax-efficient in certain income ranges, don't create RRSP room, and are taxed differently depending on whether they're eligible or non-eligible. The optimal mix depends on your personal income needs, your RRSP room and whether contributing more is valuable, your CPP strategy, and the tax rates applicable to your specific situation in the current year.
This decision gets made every year, often by default rather than by design. A coordinated approach reviews it annually with your full picture in view - corporate retained earnings, personal registered account balances, retirement timeline, and income needs - and makes a deliberate choice rather than repeating last year's approach because nobody raised the question.
Corporate Retained Earnings and the Passive Income Problem
Calgary business owners who have accumulated significant retained earnings inside their corporation face a planning challenge that many don't see coming until it's already affecting them.
The passive income rules introduced in 2018 reduce the small business deduction - which provides a lower corporate tax rate on active business income - when corporate passive investment income exceeds $50,000 in a year. For every dollar of passive income above that threshold, the business limit eligible for the small business rate is reduced by five dollars. Above $150,000 in passive income, the small business deduction is eliminated entirely.
For a Calgary business owner with $2M or more in corporate retained earnings invested in a standard balanced portfolio, this threshold is easy to breach - and the tax consequence is real. Managing the investment strategy inside the corporation with an eye on this threshold, using structures like permanent life insurance to shelter investment growth from passive income rules, or accelerating distributions to personal accounts in a tax-efficient way are all strategies that require someone looking at the corporate and personal picture together.
Planning for the Business Sale
For Calgary business owners with an eventual sale in mind, the tax planning that happens in the years before the transaction has a larger impact on after-tax proceeds than almost any negotiation at the closing table.
The Lifetime Capital Gains Exemption - currently approximately $1.275 million per eligible individual - shelters gains on the sale of qualifying small business corporation shares from tax entirely. For business owners with spouses and adult children who hold shares, multiplying that exemption across family members through a properly structured trust or share structure can shelter several million dollars of gain from tax - but the structure needs to be in place years before the sale, not weeks.
Estate freezes, share reorganizations, and trust structures used to multiply the capital gains exemption require planning horizons of at least two to three years to be effective and to survive CRA scrutiny. For Calgary business owners who are five to ten years from a planned exit, now is precisely the right time to have that conversation.
Transitioning Corporate Wealth to Personal Hands
Even without a business sale, Calgary business owners eventually need to transition accumulated corporate wealth into personal assets in a tax-efficient way. The corporation doesn't disappear at retirement - it becomes a holding company that needs to be wound down or managed strategically over time.
Options include drawing salary or dividends over time, using the capital dividend account to distribute capital gains tax-free to shareholders, implementing a shareholder loan repayment strategy, or transferring assets to a family trust. The right approach depends on the size of the retained earnings, the shareholder structure, the personal tax situation of the shareholders, and the timeline for winding down.
This is not a decision that benefits from being made reactively. It requires a plan built years in advance that coordinates corporate distributions with personal registered account contributions, retirement income needs, and estate intentions - all at the same time.
The Integration Advantage
Here's what separates Calgary business owners who build wealth efficiently from those who work just as hard and accumulate less. It's not investment performance. It's the degree to which their corporate and personal financial decisions are being made from the same plan, with the same picture in view, by someone whose mandate covers both sides of the equation.
For Calgary business owners with $500,000 or more in combined corporate and personal assets, that integration is the single highest-leverage financial decision available - and it's exactly what wealth management Calgary professionals in the Personal CFO model are built to deliver.
If you have questions, let's talk and discover the wealth management Calgary families trust to have clarity, confidence, and freedom in their financial life.
Ready to See What Integrated Corporate and Personal Planning Looks Like for Your Business?
Book a 30-minute intro call and we'll identify the coordination gaps in your current setup and show you what a unified strategy delivers for your specific situation.
Ryan Gubic is the founder of MRG Wealth Management Inc. operating as MRG Wealth (“MRG”) and is a Portfolio Manager with MRG investments of Aligned Capital Partners Inc. (“ACPI”). The opinions expressed are not necessarily those of MRG, ACPI, or Ryan Gubic. This material is provided for general information and the opinions expressed and information provided herein are subject to change without notice. Every effort has been made to compile this material from reliable sources however no warranty can be made as to its accuracy or completeness. Before acting on the information presented, seek professional financial advice based on your personal circumstances. ACPI is a full-service investment dealer and a member of the Canadian Investor Protection Fund (“CIPF”) and the Canadian Investment Regulatory Organization (“CIRO”). Investment services are provided through MRG Investments, an approved trade name of ACPI. Only investment-related products and services are offered through MRG Investments of ACPI and covered by the CIPF. Financial planning and insurance services are provided through MRG. MRG is an independent company separate and distinct from MRG Investments of ACPI.
Dollars and Sense
Discover more
Dive into some advice directly from our Founder and Personal CFO.
What Happened in the Markets October 2026